New Mortgage LLPA Changes: What You Need to Know
On May 1, 2023, in a single moment, the majority of new mortgages in the U.S. will change. These changes are designed to make the LLPA more accurate and transparent. Good news and bad news.
The Loan Level Pricing Adjustment (LLPA) is a formula that lenders use to calculate the interest rate on a mortgage. The LLPA takes into account a number of factors, including the borrower’s credit score, debt-to-income ratio, and the type of loan.
What do you mean by fees or costs?
This refers to Loan Level Price Adjustments (LLPAs) imposed by Fannie Mae and Freddie Mac (the “agencies”), the two entities that guarantee a vast majority of new mortgages. LLPAs are based on loan features such as your credit score, the loan-to-value ratio, occupancy (owner vs non-owner occupied homes), and, most recently, your debt-to-income ratio
Here are some of the key changes:
- The LLPA will now take into account the borrower’s credit history for the past 24 months, instead of just the past 12 months.
- The LLPA will now include a new factor for borrowers who have recently paid off debt.
- The LLPA will now be more transparent, with lenders required to disclose the specific factors that are used to calculate the interest rate.

A Few other Examples of LLPA Mortgage changes:
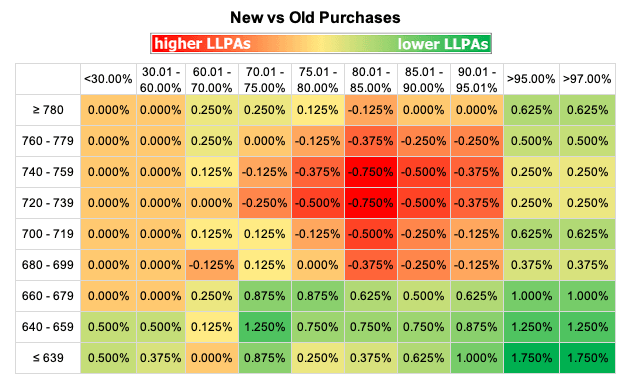
- There are new credit score bands at 760+ and 780+.
- There is more differentiation in high-balance vs non-high-balance ARM loans (uncommon… most ARMs are not done through the agencies)
- Several changes to 2-4 unit property LLPAs
- There’s a new generic LLPA for “subordinate financing” (a 2nd loan or HELOC) whereas the previous LLPAs were more granular depending on the LTV of first loans vs subordinate loans
- BIG increases in fees for many “Cash-Out” loans
Source: Mortgage News Daily
What do these LLPA changes mean for you?
If you are planning to buy a home in 2023 and beyond, it is important to be aware of these changes to the LLPA. The changes could affect the interest rate you are offered on your mortgage by any lender as these changes are implemented by the FHFA, Federal Housing Finance Agency.
In general, borrowers with good credit and low debt-to-income ratios are likely to see little to no impact on their interest rates. However, borrowers with less-than-perfect credit or higher debt-to-income ratios could see their interest rates increase.
If you are concerned about how the LLPA changes could affect your mortgage, it is a good idea to talk to a mortgage lender. They can help you understand how the changes will impact your specific situation and can help you find the best mortgage for your needs.
It is important to note that these changes occur from time to time based on the overall U.S. market conditions and patterns that the FHFA sees in order to level things to make homeownership as fair and balanced as possible for all potential homeowners. The changes are an adjustment, and not something that should steer a would be home buyer to the sidelines to play the waiting game.
When you look at it from a monthly fluctuation perspective, in most cases these changes may only change your monthly payment approximately $30-40 higher or lower depending on where you fall. If that is a concern, looking at the chart, the less you put down (ironically), the greater your benefit to not pay extra in the LLPA rate adjustments that are applied to all lenders (yes, all) at the base level by the FHFA, Fannie Mae, and Freddie Mac.
Have more questions on how it can benefit you? Contact us
Find out what your rate would be today.
Here are some additional resources that you may find helpful:
- Mortgage News Daily
- The Federal Housing Finance Agency’s (FHFA) website: https://www.fhfa.gov/ has more information about the LLPA changes.
- The Consumer Financial Protection Bureau’s (CFPB) website: https://www.consumerfinance.gov/ has more information about mortgage lending.
- The National Association of Mortgage Brokers’ (NAMB) website: https://www.namb.org/ has a mortgage calculator that you can use to estimate how the LLPA changes will affect your interest rate.