A lower payment at the start of a mortgage can give your budget breathing room. A 2-1 buydown does that for two years. The important part is knowing what the payment becomes afterward and being comfortable with it even if rates never fall.

How a 2-1 buydown works
A funded buydown account covers part of the scheduled principal-and-interest payment. For an illustrative fixed note rate of 7%, your first-year contribution is calculated using 5%; the second year uses 6%; the third year begins the full 7% payment. The mortgage note rate remains 7%. Taxes, home insurance, mortgage insurance and HOA costs are separate and can change.
The subsidy is paid upfront. Who may fund it, which transactions qualify and how credits are treated depend on the loan program and selected lender. Our team reviews those rules before you negotiate an offer.
Compare the temporary buydown options

1-0: one year at a payment calculated one percentage point below the note rate. 1-1: two years at one point below, with the full payment starting in year three. 2-1: two points below in year one, one point below in year two. 3-2-1: three, two and one point below in the first three years, where available. These are payment illustrations, not changes to the contracted note rate.
Use our temporary buydown calculator to compare the payment steps and estimated subsidy. Bring the result to our team so we can check the program, costs and full-payment budget.
Does a temporary buydown help you qualify?
Plan to qualify using the full mortgage payment required by the loan program. Fannie Mae requires qualification at the note rate without using the reduced buydown rate. A temporary buydown should not be the reason an otherwise unaffordable loan looks affordable.
Paying discount points for a permanent rate reduction is a different choice. We compare that cost with a temporary subsidy, a price reduction and a credit toward closing costs on the same loan assumptions.
Using seller credits thoughtfully
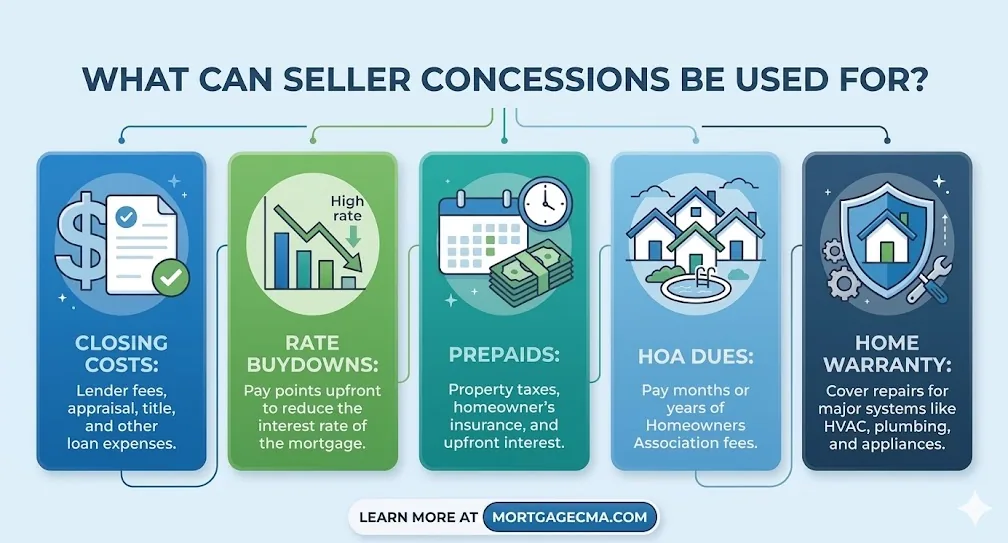
A seller or builder may help fund the subsidy if your program permits it. The credit must fit the contract, applicable contribution limits and actual eligible costs. Check the seller concessions calculator, then let our team and your agent coordinate the offer. Increasing the price to request credits still has to work for your budget and the appraisal.
Buying now versus waiting
Home prices and mortgage rates can rise or fall. Buying sooner does not guarantee appreciation, and refinancing later is never guaranteed. Compare a purchase you can afford today with the rent, savings, transaction costs and timing involved in waiting. For Colorado buyers, property taxes, insurance and location matter as much as the introductory payment.
Build a plan that survives the payment increase
Before deciding, check your cash left after closing, the full monthly housing payment, when each payment step occurs and the buydown agreement’s treatment of unused funds if you sell or refinance. Ask our team to compare those choices across our wholesale lender network.
Start my homebuying plan or schedule a conversation with our team. We can review the numbers before you commit to a financing strategy.
Guideline source: Fannie Mae temporary interest rate buydowns. Reviewed October 7, 2026.
*Information, scenarios, and calculations are for educational and illustrative purposes only, not a loan offer, a commitment to lend, a rate quote or an approval. Programs, costs and qualification requirements depend on the borrower, property, selected lender and current guidelines. Examples are not guaranteed results. Our team can review the details for your situation.