Before you start saving listings, take a look at what a mortgage lender will see. Your credit reports can affect the programs available to you, loan pricing and mortgage insurance. You do not need a perfect score to begin planning. You do need a clear picture.
The most useful credit plan is specific: find errors, protect payment history and decide which balances to tackle without draining the money you need for a home purchase. These ten steps give you a place to start.
1. Read all three credit reports
Get your reports through AnnualCreditReport.com, the official source. Review Equifax, Experian and TransUnion because the information may differ. Look for unfamiliar accounts, incorrect balances and payments marked late that you made on time. A credit report and a credit score are different things; the report shows the information behind the score.
2. Correct errors with documentation
If something is wrong, dispute it with the reporting company and the business that supplied the information. Keep copies of supporting records and your correspondence. The CFPB’s dispute instructions and sample letters explain the process. For suspected identity theft, use IdentityTheft.gov. Dispute inaccurate information, rather than trying to remove accurate history.
3. Protect every payment due date
Set reminders or automatic minimum payments, and check that the account has enough money for them. If you are struggling to make a payment, contact the creditor early. Consistent payments build a stronger record over time. See the CFPB’s credit rebuilding guidance for practical habits.
4. Lower revolving balances thoughtfully
Credit utilization compares your reported card balances with your available limits. A $1,000 balance on a $5,000 limit is 20% utilization. Lower utilization can help, but 30% is not a magic approval line. Scoring models consider your overall profile and individual accounts. You do not have to carry interest-bearing debt to build credit.
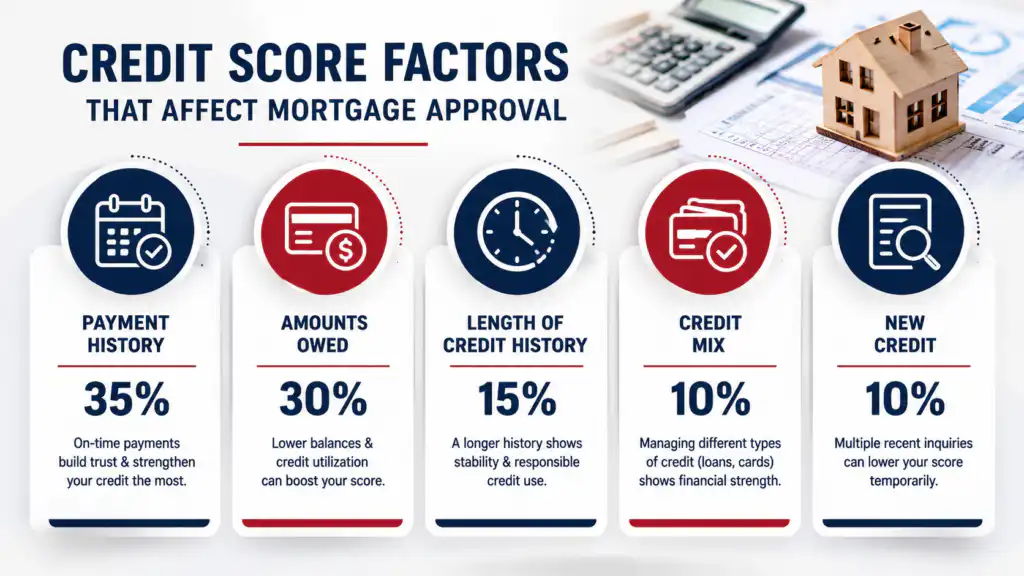
The chart in plain text: FICO’s general breakdown is payment history 35%, amounts owed 30%, length of credit history 15%, new credit 10% and credit mix 10%. Utilization is part of amounts owed, not that entire category. The weight of a factor can differ with the credit profile. FICO explains these factors here.
5. Keep useful older accounts in perspective
Closing a card can reduce available credit and increase utilization. Keeping an account open is not automatically the right answer either, particularly if fees or overspending are a problem. Review the effect before making changes shortly before a mortgage application.
6. Pause unnecessary new credit
A new car loan, store card or personal loan can change both your credit profile and monthly debt obligations. Talk with your mortgage advisor before applying for new credit during your home search or while a loan is processing. Do not assume a small payment is too small to matter.
7. Separate your credit score from your DTI
Debt-to-income ratio compares monthly debt payments with gross monthly income. It is an underwriting measure, not the same thing as credit utilization. Paying a balance down may help your score without immediately changing the payment used to qualify. Our debt-to-income calculator can help you explore an estimate; the lender determines the qualifying amounts.
8. Understand mortgage credit checks
Checking your own reports does not damage your score. A lender’s hard inquiry can affect it. The score in a consumer app may differ from the model used for a mortgage. Mortgage-shopping inquiries can be grouped within a model-dependent window, so coordinate timing with your advisor. Read the CFPB explanation of mortgage credit checks rather than assuming every inquiry works the same way.
9. Preserve cash for the purchase
Do not empty your savings solely to chase a score. You may need funds for the down payment, closing costs, reserves and life after closing. Ask us to compare the effect of a debt payoff against the cash you would have left. The right sequence depends on the loan and your finances.
10. Get a plan before making major changes
Collections, disputed accounts, thin credit history and recently paid debts can require different approaches. Ask for a mortgage-readiness review before opening accounts or moving large amounts of money. No one can honestly promise a particular score increase or an approval on a fixed schedule.
A practical first week
Day one: collect the three reports. Next: flag errors and verify payment reminders. Then: list card balances, limits and monthly payments. Finally: bring that picture, your savings and your buying timeline to a mortgage conversation. Share sensitive documents through a secure process, not an ordinary website comment.
Questions worth answering
How quickly can my credit score improve?
It depends on the information changing, creditor reporting dates and the scoring model. Lower reported balances may show up after an account updates. Errors and older negative history can take longer. A specific increase is not guaranteed.
Should I pay every debt off before applying?
Not necessarily. Compare the qualifying benefit with the cash needed for your purchase and reserves. Ask for a review before making a large payoff.
What score do I need for a mortgage?
Requirements depend on the program, lender and underwriting method. Credit is only one part of the review, alongside income, assets, debts and the property. We can review the programs that fit your actual file.
Can you help if I am not ready to buy yet?
Yes. An early conversation can identify what to work on and when to check back. It is easier to plan before you have an offer deadline.
Turn the credit checklist into your homebuying plan
Cederholm Mortgage Advisors can compare lenders and programs using your circumstances, then explain the payment, costs and next steps. Contact Paul Cederholm and our team or start your homebuying plan.
Updated October 8, 2026.
*Information, scenarios, and calculations are for educational and illustrative purposes only, not a loan offer, a commitment to lend, a rate quote or an approval. Programs, costs and qualification requirements depend on the borrower, property, selected lender and current guidelines. Examples are not guaranteed results. Our team can review the details for your situation.