The right house still needs the right financing plan. A lower payment today can come with a higher payment later. A seller credit can save cash at closing, but only if your loan allows it and you have eligible costs to cover. Those details belong in the conversation before you write an offer.
This home buyer’s guide focuses on financing and offer strategy. For the buying sequence, start with our first-time home buyer guide.
Start with three numbers, not just a rate
- Your comfortable monthly housing budget: principal and interest, taxes, home insurance, mortgage insurance if applicable, and HOA dues. Leave room for maintenance and utilities.
- Your cash needed to close: down payment, closing costs and prepaid expenses, after deposits and approved credits.
- Your cash left afterward: moving costs, repairs and a reserve you can actually live with.
Try our mortgage calculators, then bring us your price range and down payment. Pre-approval is a checkpoint; final approval still depends on the borrower, property and loan conditions.
Four financing strategies, compared
| Strategy | What it does | Main tradeoff |
|---|---|---|
| Temporary buydown | Subsidizes early payments for a limited period. | Payments rise as the subsidy ends. |
| Permanent points | Upfront cost for a lower contracted rate. | Needs time to recover the extra cost. |
| ARM | Initial rate period, followed by adjustments. | Future rate and payment can increase. |
| Seller credits | Cover permitted closing expenses. | Program and actual-cost limits restrict use. |
Temporary buydowns: breathing room with an end date
A temporary buydown funds part of your early payments without changing the note rate. A 2-1 arrangement typically subsidizes payments calculated two percentage points below that rate in year one and one point below it in year two. Your full note-rate payment follows.
Available structures can include 1-0, 1-1, 2-1 and 3-2-1, depending on the program. Under Fannie Mae’s rules, borrowers qualify at the note rate. Compare each year with our temporary buydown calculator. Do not build a budget around a hoped-for refinance.
Permanent points: evaluate the time needed
Discount points exchange an upfront charge for a lower interest rate. One point equals 1% of the loan amount; it does not buy a fixed amount of rate reduction. Ask for comparable options with and without points. The CFPB explains points and lender credits in plain language.
$4,000 in additional upfront cost ÷ $100 in monthly savings = 40 months.
Would you expect to keep that loan beyond then?
That simple calculation leaves out opportunity cost and differences in loan balances. We can compare total costs over your timeline. Selling or refinancing early may leave you short of recovering the points.
ARMs: read the adjustment rules
An adjustable-rate mortgage can suit some borrowing plans, but the initial rate is only part of the contract. Check how long it lasts, how often adjustments happen, the index and margin, and the first, subsequent and lifetime caps. Calculate a payment you could face after an increase. An ARM’s starting rate is not always lower than a fixed-rate alternative.
You may stay longer than expected or be unable to refinance when you want. The CFPB’s ARM handbook is a useful reference when reviewing the terms.
Seller credits: negotiate toward your real need
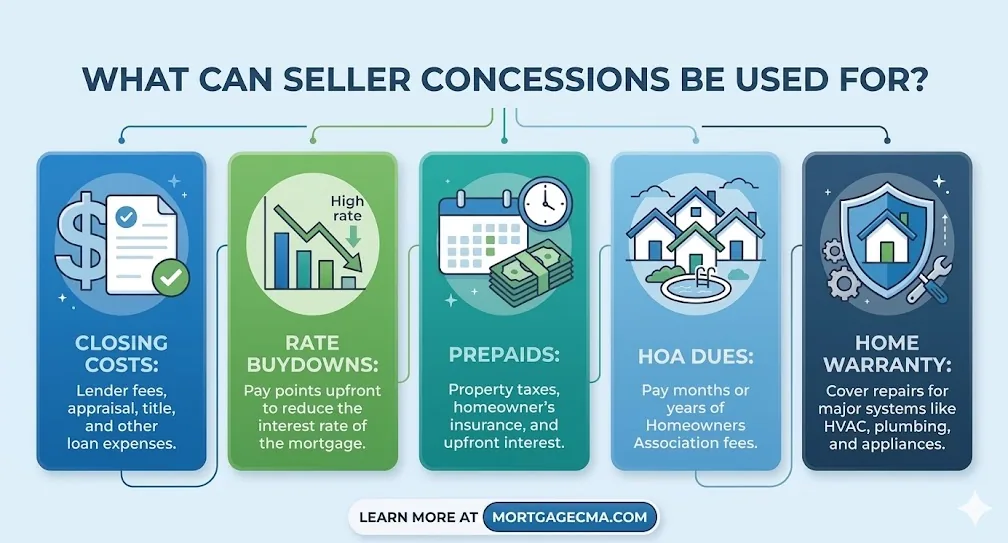
Seller credits can cover eligible closing costs and, where permitted, points or a temporary buydown. They do not replace the required down payment. Check the allowed amount before putting a credit into the contract.
For Fannie Mae principal-residence or second-home loans, financing concession ceilings are 3% above 90% LTV, 6% at 75.01%–90% LTV, and 9% at 75% LTV or lower. Investment properties have a 2% ceiling. Limits use the lesser of price or appraised value; usable financing concessions cannot exceed eligible closing costs. Other programs differ. See Fannie Mae’s guidelines and our seller concessions calculator.
Build the offer with your agent and mortgage advisor
- Name the problem: cash at closing, the ongoing payment or early ownership expenses?
- Compare a price reduction with a credit: they affect your loan and cash needs differently. Neither is automatically better.
- Check appraisal and program rules: contract credits still have to fit the financing and supported property value.
- Keep comparisons fair: same loan amount, term, lock period and assumptions. Review points, APR, full payment and cash to close.
- Document the agreement: have your agent prepare the contract terms and your financing team confirm permitted treatment.
A seller may decline a credit. Build an offer you can support without depending on a concession that has not been accepted.
Questions worth answering
Can I combine seller credits and a buydown?
Sometimes. The program must allow the structure, and seller-funded costs must fit the applicable contribution limits. One credit cannot be counted twice.
Does a temporary buydown help me qualify for more?
Do not assume it does. Fannie Mae requires qualification at the note rate. Ask how your selected program evaluates the payment.
Which option saves the most?
It depends on costs, how long you keep the loan and what happens after an introductory period. Compare the whole scenario, including a less favorable outcome.
Put your offer and financing on the same page
Share your target price, available cash and timeline. Paul Cederholm and the team at Cederholm Mortgage Advisors can help you compare practical choices before you commit. Start my homebuying plan or ask our team a question.
Reviewed October 8, 2026.
*Information, scenarios, and calculations are for educational and illustrative purposes only, not a loan offer, a commitment to lend, a rate quote or an approval. Programs, costs and qualification requirements depend on the borrower, property, selected lender and current guidelines. Examples are not guaranteed results. Our team can review the details for your situation.