Conforming Loan Limits
Homebuyers, have you been eyeing that dream home just out of reach? Well, the Federal Housing Finance Agency (FHFA) has just made it a bit easier to make those dreams a reality by increasing the conforming loan limits for 2026.
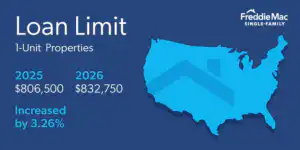
For 2026, the national standard conforming loan limit for a single-family home will increase to $832,750, up from $806,500 in 2025. This increase reflects the overall rise in home prices across the country.
What are Conforming Loan Limits?
Conforming loan limits are the maximum mortgage loan amounts that Fannie Mae and Freddie Mac, two government-sponsored enterprises (GSEs), are willing to purchase for Conventional Loans (conforming to their guidelines, thus the term, conforming loan limits). These limits are set annually by the FHFA and are based on changes in the national average home price.
What does this mean for homebuyers?
The increase in conforming loan limits means that more homebuyers will be eligible for conventional loans, which typically have lower interest rates and fees than jumbo loans. In Denver County, Colorado, housing prices are higher than the national average, so FHFA has what is known as a high balance loan limit, which is set at $862,500 in many areas in Colorado for 2026.
Be sure to confirm your loan limit in the area you are looking to buy, and also be aware that such loan limits may be different for FHA or VA loans, which typically hav a Low-Cost Area “Floor” currently set at $541,287 for 2026and a High-Cost Area “Ceiling” set at $1,249,125 for 2026.
The Home Equity Conversion Mortgage, also known as HECM or Reverse Mortgage, maximum claim amount will increase from $1,209,750 in calendar year 2025 to $1,249,125 for FHA case numbers assigned on or after January 1, 2026.
Areas in Eagle County, Garfield County, and Pitkin County, Colorado, where cities like Vail, Boulder, and Breckenridge reside, and where real estate is even at a higher premium, have high balance loan limits that can go as high as $1,249,125 for a single-family home. For anything higher than the conforming loan limit or high balance loan limit in the area you’re looking to buy, you would need to look at a Jumbo Loan. Jumbo loans are loans that exceed the conforming loan limits and are typically offered by private lenders. We work with those as well and can find the best Jumbo Loan for your needs.
Base Loan Limit Values:
The following chart shows the 2026 maximum baseline conforming limit values for mortgages secured by properties that are not located in designated high-cost areas.
| Number of Units | Maximum loan limits for properties in designated high-cost areas NOT in Alaska, Hawaii, Guam and U.S. Virgin Islands | Maximum loan limits for properties in designated high-cost areas in Alaska, Hawaii, Guam and U.S. Virgin Islands |
|---|---|---|
| 1 | $832,750 | $1,249,125 |
| 2 | $1,066,250 | $1,599,375 |
| 3 | $1,288,800 | $1,933,200 |
| 4 | $1,601,750 | $2,402,625 |
Loan Limits in High-Cost Areas*
For properties located in designated high-cost areas*, we’ll purchase mortgages with original loan amounts up to the following limits:
| Number of Units | Maximum loan limits for properties in designated high-cost areas NOT in Alaska, Hawaii, Guam and U.S. Virgin Islands | Maximum loan limits for properties in designated high-cost areas in Alaska, Hawaii, Guam and U.S. Virgin Islands |
|---|---|---|
| 1 | $1,249,125 | $1,873,675 |
| 2 | $1,599,375 | $2,399,050 |
| 3 | $1,933,200 | $2,899,800 |
| 4 | $2,402,625 | $3,603,925 |
*Actual loan limit values for certain high-cost areas, as determined by FHFA, may be lower than the maximum high-cost area loan limits identified. Loan limit values are available on the FHFA website

What to Consider Before Applying for a Mortgage
Before you apply for a mortgage, it is important to consider your financial situation and make sure you can afford the monthly payments. You should also shop around for the best interest rates and terms.
Here are some tips for getting the best mortgage possible:
- Get pre-approved for a mortgage. This will give you a good idea of how much you can afford to borrow and will make you a more competitive buyer.
- Shop around for different lenders. Compare interest rates, fees, and terms from multiple lenders before you choose one.
- Make sure your credit is in good shape. Your credit score will affect the interest rate you qualify for.
- Put down as much as you can afford. The more money you put down, the lower your monthly payments will be.
Looking to Buy a Home in 12 Days or 12 months in Colorado?
If you are thinking about buying a home, now is a great time to start talking to a mortgage broker or mortgage lender. With the new conforming loan limits, you may be able to buy a bigger home and get a conventional loan with a lower interest rate than you thought possible. Schedule a Consultation to find out what your best options are.