 Conventional
Explore as little as 3-5% down payments, mortgage insurance, and flexible property choices with Fannie Mae and Freddie Mac.
Home / Areas We Serve / Cherry Creek
DENVER NEIGHBORHOOD MORTGAGE GUIDE
A home in Cherry Creek, Denver should fit your life and your finances. Compare purchase and refinance options with Paul Cederholm and the team, including the full payment, cash to close and property details that can change the plan.
Cherry Creek brings Denver’s shopping, dining and arts scene close to home. Start with your goals, then bring us the address.
Cherry Creek brings Denver’s shopping, dining and arts scene close to home. A stroll through Cherry Creek North feels different from time along the creek trail, and both belong in the neighborhood story. Buyers will find detached homes, contemporary duplexes, townhomes and condominium living worth comparing on their own terms.
The legal ownership structure matters more than the listing label. A townhome may be a condominium for lending purposes. Ask for the deed description, association information and master insurance before assuming a property will be reviewed like a detached house.
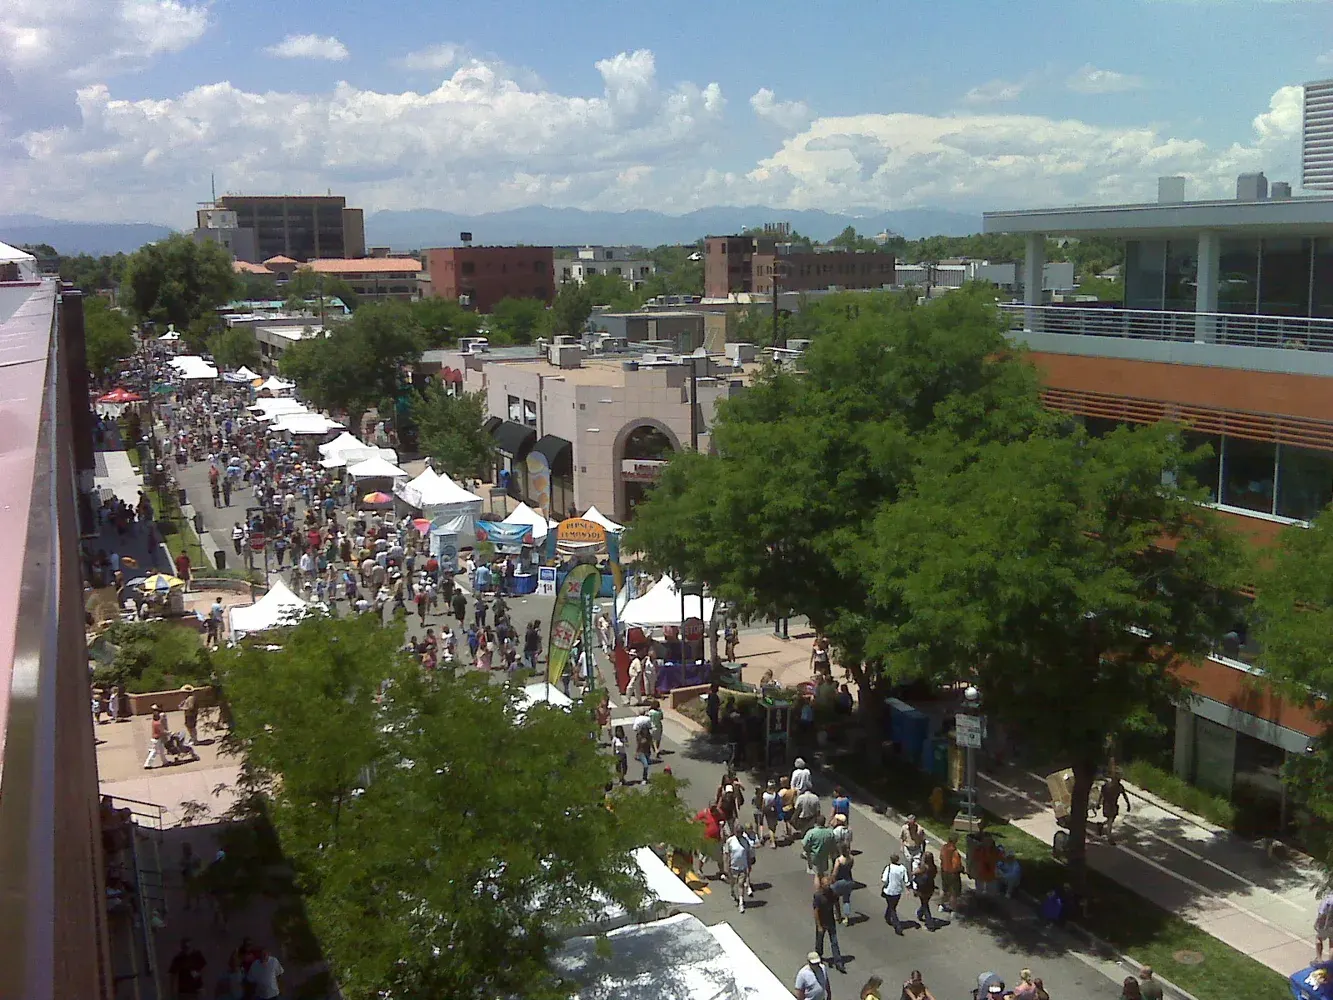
Neighborhood dining, galleries and outdoor events create an easy reason to get out of the house. Explore the streets you would actually use rather than treating every Cherry Creek address as the same experience. Check parking arrangements and the route between your home and favorite stops.
The relevant jurisdiction is the City and County of Denver. Confirm the parcel, tax record and legal property type. A neighborhood name does not replace the documents. Include taxes, home insurance, mortgage insurance when applicable, HOA dues and any district charges in the monthly comparison.
Compare the full payment with HOA dues and insurance included. For a larger purchase, ask how the lender treats assets, reserves and any other properties you own. A lower headline rate is only useful when the closing costs and cash requirements also fit your plan.
Begin with a payment you can live with and the cash you want to retain. We compare suitable lenders using the same purchase price, down payment, term and property assumptions, then explain what changes when a loan includes mortgage insurance, points or a funding fee.
Before your first offer, organize your income documents, assets and target payment. Ask your agent for the property records and inspection timeline. Colorado assistance programs may be available through participating lenders, subject to borrower and property rules. Review down payment assistance.
Conventional, FHA and VA routes may be worth comparing for eligible borrowers and properties. Larger loan amounts can call for jumbo or portfolio options. Self-employed buyers can review documentation alternatives. Compare the full payment with HOA dues and insurance included. For a larger purchase, ask how the lender treats assets, reserves and any other properties you own. A lower headline rate is only useful when the closing costs and cash requirements also fit your plan.
Home purchase guide · Compare loan options · Seller credits calculator
Compare purchase, refinance and affordability scenarios, then let our team help turn the estimate into a financing plan.
Explore the loan guides below, then compare the borrower and property requirements with our team. A financing program should fit the actual home and your intended use.
Compare home purchase, refinance, equity and specialty financing paths. Start with the guide that fits your goal, then review the borrower and property requirements.
ConventionalExplore as little as 3-5% down payments, mortgage insurance, and flexible property choices with Fannie Mae and Freddie Mac.
 FHA
Review lower FHA credit limit options, as low as 3.5% down payment, and get into homeownership vs renting.
 VA
Learn the benefits and eligibility for qualified military service members, veterans and spouses with a possible zero-down option for eligible borrowers.
 USDA
Check how rural property location and household income affect USDA options to qualify for little to no money down.
 Jumbo
Learn how larger loan amounts above conforming loan limits change the documentation and reserves needed.
 Non-QM / Alternative Financing
Explore Non-QM alternative financing paths outside standard guidelines for self-employed, 1099, variable income, etc.
 Reverse Mortgage
Review how reverse mortgages (HECM) work for purchase or refinance and the ongoing homeowner obligations.
 HELOC / Home Equity
Compare options to access your home equity to consolidate debt, make home improvements, buy a second home, etc.
 Down Payment Assistance
We can help you find Colorado assistance programs to help you as a first-time homebuyer with little to no money down.
Explore first-lien HELOC financing that pairs home debt with cash-flow account features, compare daily-balance interest, deposits, withdrawals and repayment discipline.
Compare rental purchase and refinancing options, including DSCR and short- or long-term rental considerations.
Plan construction draws, builder coordination and one-time-close or two-close financing.
Review acquisition, renovation funds, short-term repayment and your sale or refinance plan.
Check build timing, access, utilities and the differences between raw land and a prepared homesite.
Explore multifamily, standalone buildings and individual commercial sites with property-specific underwriting.
For a Cherry Creek condo, request the association budget, reserves, insurance and assessment information early. For a larger detached home or duplex, compare loan amount, reserves and appraisal requirements. Parking, storage and common-area obligations should be clear in the documents.
Request current tax figures and a home insurance quote for the address. Review association budgets, insurance and assessments when applicable. Clarify what you own, which expenses are shared and whether the payment estimate accounts for them.
Use local community resources to explore the setting. Your agent, title company, insurer and lender can help reconcile the property records and financing documents. For a condo, Fannie Mae’s project standards explain why the building review matters alongside your application.
Start with a goal: a different term, payment, cash access or financing for improvements. Bring the current mortgage statement, tax record, insurance and any second lien. We can compare keeping the loan, replacing it or adding home-equity financing for your Cherry Creek property.
Compare closing costs, points, the new balance and interest over the time you expect to keep the loan. A longer term can lower the payment while increasing total cost. Compare the full payment with HOA dues and insurance included. For a larger purchase, ask how the lender treats assets, reserves and any other properties you own. A lower headline rate is only useful when the closing costs and cash requirements also fit your plan.
Paul Cederholm (NMLS #1697336) is a mortgage advisor and real estate financing strategist with Cederholm Mortgage Advisors, powered by Edge Home Finance (NMLS #891464). Our team helps buyers and homeowners in Cherry Creek, Denver compare lenders and plan their next move by phone or video. Contact our team.
Excellent rating
Based on 47 reviews
 Paul and his team helped me with a very complicated transaction for a cash out mortgage. I would highly recommend him.
 Christopher MSeptember 23, 2026Paul was great. He helped us understand our loan better and put our needs first. I’d strongly recommend his services. Throughout our home buying process, Paul Cederholm demonstrated the highest level of professionalism throughout our home loan process, an amazing ability to explain complex mortgage terms in simple language and a willingness to work evenings and weekends to meet our closing deadline. We got our home purchase loan in Chicago thanks to Paul Cederholm. I would absolutely recommend Paul Cederholm for your home loan because I would recommend Paul. You can trust him and he is very informative. We can't recommend Paul Cederholm enough for your home financing needs.
 Jayden FSeptember 1, 2026My overall experience working with Paul was fantastic! All his help made the whole process seem easy. Throughout our home buying process, Paul Cederholm demonstrated a talent for making the mortgage process seamless and stress-free, truly professional lending services that exceeded our expectations and a knack for shopping rates and locking in an amazing deal for us. He is humble and easy-going, which made us feel at ease. I would absolutely recommend Paul Cederholm for your home loan because paul is a truly amazing advisor: el mejor! Without his help, our dream of owning our first home would not have been possible. After our introductory call ended, my husband and I looked at each other and said, "He is the one!" We were absolutely right. Paul exceeded our expectations by offering excellent advice and answering our questions before we even had to ask them (mind reader!). Paul always had our best interests at heart, and his dedication and passion showed in every conversation. We are thankful to have worked with someone trustworthy and honest; someone who went above and beyond for us. Thank you, Paul, for taking all of our doubts and worries away. Thank you for cheering us on! We absolutely recommend you and your team to anyone looking for the best mortgage advisor. We can't recommend Paul Cederholm enough for your home financing needs.
 Diana MAugust 10, 2026Exceptional experience with Paul and his team! We knew we wanted to work with Paul not long into our introductory call. He put us at ease as he explained all the details of what it would take to get into our first home. Numbers are scary when it comes to such a large purchase, but he walked us through the documents in a way that was easy to comprehend. He made sure we understood the information and answered all the questions we had before proceeding to the next task. He was always available for a call, through text, and email. Never once did we feel uncomfortable or like we were not being heard and understood. We got the best rate available to us based on our information and also helped us get a rate buy-down! Thank you, Paul and your team, for everything you did. We look forward to working with you again should the time come to refinance or get into a different home. Paul Cederholm brought impressive expertise across mortgage products that helped us find the perfect fit, incredible dedication to finding us the best mortgage rate and a willingness to work evenings and weekends to meet our closing deadline. I'd tell anyone looking for a home loan to call Paul Cederholm — highly recommend Paul and his team as we felt comfortable, understood, and empowered throughout the entire process!. I would highly recommend Paul Cederholm — truly an exceptional mortgage professional.
 Angel MAugust 10, 2026Excelente atendimento de Cederholm.
 Janaína VMay 28, 2026Working with Paul and his team was an absolute dream! We had a particularly complex transaction, Paul made navigating feel easy and less stressful.
 Kayla bMay 12, 2026Paul and his team were absolutely amazing! Insanely fast response time to any question I had and amazing explanations throughout the whole process. I can’t imagine using another broker ever again!
 Samantha CApril 18, 2026If you are looking for a mortgage broker for your next home purchase, I highly recommend Paul Cederholm and his team at Cederholm Mortgage Advisors 🏡. Paul helped me plan the financing for my new home, and I am so grateful for his guidance throughout the process. At the beginning, I felt nervous because the home buying process can feel very intimidating. With Paul’s care, patience, and expertise, I grew into a confident home buyer by the time we reached closing 🌿. Paul was always available to answer my questions and explained everything in a clear, supportive, and non-intimidating way. He stayed one step ahead throughout the loan process and helped ensure my loan approval moved along quickly and smoothly. Paul also has a wonderful team. Their attention to detail and clear communication helped me feel supported and never overwhelmed during the process 🌸. I truly loved working with Paul. He was wonderful to have by my side during such an important step in my life. If you are looking for a knowledgeable and caring mortgage advisor who will guide you every step of the way, I wholeheartedly recommend Paul Cederholm and his team.
 Nancy SMarch 11, 2026Buying my first house was an exceptional experience because Paul was tremendously helpful, and communicative. I can’t thank him and his team enough and highly recommend!!!
 Bianca RDecember 27, 2025Verified by TrustindexTrustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more
Read more about Paul Cederholm and our team on Google Business Page and Experience.com.
Tell us your timing, target payment and whether you are buying or refinancing in Cherry Creek. Share a listing or current loan statement when you have one. We can compare scenarios, identify missing documents and help you prepare for the next step. Once a property is chosen, update the numbers using its actual taxes, insurance and association costs.
No. The legal ownership form determines whether condominium project standards apply. The lender will review title and association documents rather than relying on the property’s marketing name.
For a Cherry Creek condo, request the association budget, reserves, insurance and assessment information early. For a larger detached home or duplex, compare loan amount, reserves and appraisal requirements. Parking, storage and common-area obligations should be clear in the documents.
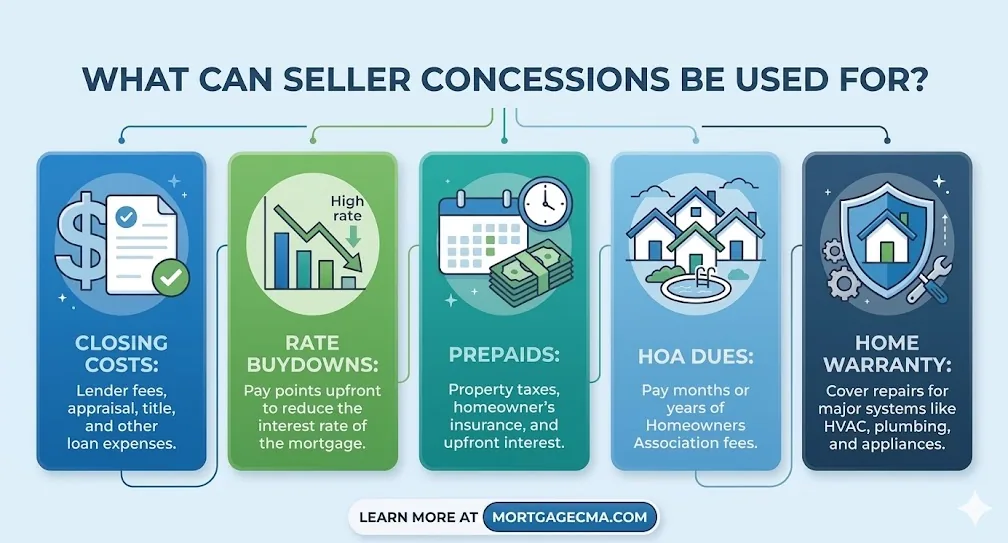
Yes. The program, occupancy, down payment and eligible closing costs affect the permitted credit. A temporary buydown reduces scheduled borrower payments for a limited period; permanent points may lower the note rate. Compare the subsidy or upfront cost with the full payment and your expected loan timeline.
No. The legal ownership form matters. A home marketed as a townhome may be a condominium, with project and insurance review requirements. Ask for title and association documents early.
Before making an offer or committing to a refinance. Share income documents, available funds and the property details early so the financing and cash-to-close estimate can be reviewed before deadlines become tight.
*Information, scenarios, and calculations are for educational and illustrative purposes only, not a loan offer, a commitment to lend, a rate quote or an approval. Programs, costs and qualification requirements depend on the borrower, property, selected lender and current guidelines. Examples are not guaranteed results. Our team can review the details for your situation.




Planning a purchase or refinance in Cherry Creek? Start with a quick, no-obligation conversation about your payment, property and next move.