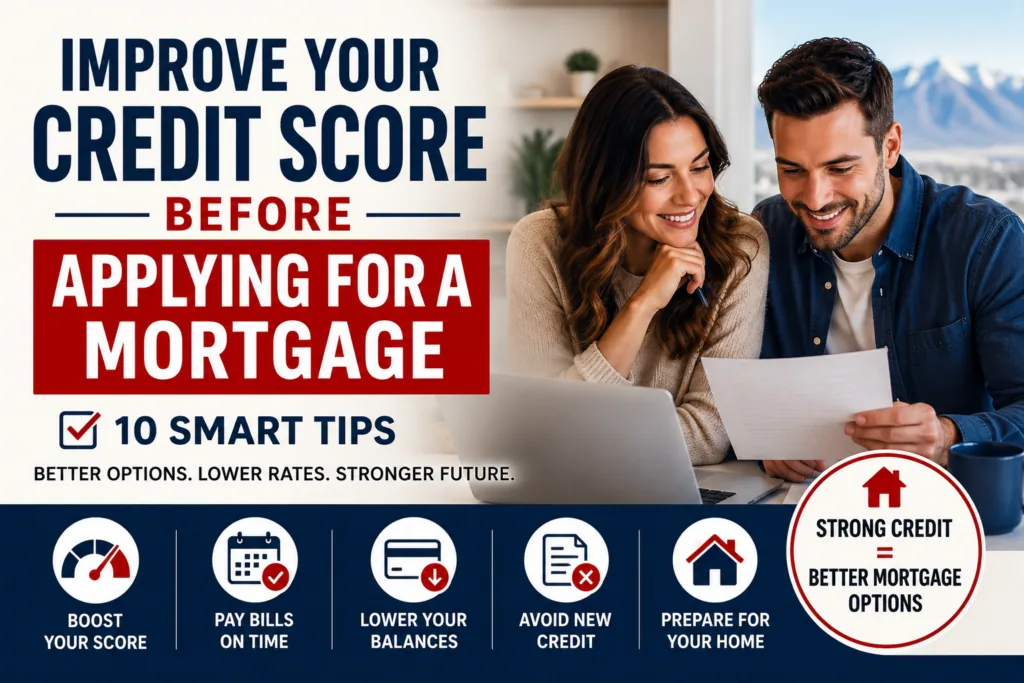
Before you start saving listings, take a look at what a mortgage lender will see. Your credit reports can affect the programs available to you, loan pricing, and mortgage insurance. You do not need a perfect score to begin planning. You do need a clear picture.
The most useful credit plan is specific: find errors, protect payment history, and decide which balances to tackle without draining the money you need for a home purchase. These 10 ways to improve your credit score for a mortgage give you a good place to start.
1. Read all three credit reports
Dispute any inaccuracies. If you spot errors in your credit reports, don’t hesitate to take action. You can file a dispute online with the credit bureaus, and they’re required to investigate your claims. This process can take some time, but correcting inaccuracies can lead to a boost in your credit score, which is crucial for securing a mortgage. Keep track of your disputes and follow up if you don’t see results. Remember, every point counts when it comes to your credit score!
Pay your bills on time. One of the biggest factors affecting your credit score is your payment history. Making timely payments on your bills, including credit cards, loans, and utilities, shows lenders that you’re responsible with your finances. Set reminders on your phone or automate your payments if you’re worried about missing due dates. This simple habit not only helps your credit score but can also save you from late fees and penalties.
Keep credit card balances low. Your credit utilization ratio, which is the amount of credit you’re using compared to your total available credit, plays a significant role in your score. Aim to keep your balances below 30% of your credit limit. If possible, pay off your balances in full each month to maximize your score. Even a small reduction in your balances can make a noticeable difference in your credit standing.
Limit new credit inquiries. When you apply for new credit, lenders conduct a hard inquiry that can temporarily lower your score. While it’s important to shop around for the best mortgage rates, try to limit the number of times you apply for new credit in the months leading up to your mortgage application. Too many inquiries can raise red flags for lenders, potentially impacting your chances of approval. Keep your credit applications focused and strategic.
2. Correct errors with documentation
Also, don’t forget to regularly check your credit report for errors. Mistakes can happen, and they could be dragging your score down without you even realizing it. If you spot anything amiss, take action right away by disputing it with the credit bureau and the creditor involved. Having clear documentation and following the right steps can make a big difference in getting those errors corrected. Maintaining a good credit score requires vigilance and proactive management. In addition to correcting errors, consider setting up alerts for any unusual activity on your accounts to catch potential fraud early.
3. Protect every payment due date
It’s crucial to stay on top of your payment schedule. Consider setting up alerts on your phone or using automatic payments to avoid any late fees. If you ever find yourself in a tight spot financially, don’t hesitate to reach out to your creditor; they may offer options to help you through it. Remember, building that reliable payment history can significantly enhance your credit score over time. Establishing a budget can also help you manage your finances more effectively, making it easier to meet payment deadlines. Prioritizing financial education can empower you to make informed decisions regarding your credit.
4. Lower revolving balances thoughtfully
Another great tip is to keep an eye on your credit utilization ratio. Aim to use less than 30% of your available credit; this shows lenders you’re not overly reliant on credit. You can achieve this by paying down your balances more frequently or requesting a credit limit increase. Plus, don’t forget to check your credit report for any errors—disputing inaccuracies can give your score a nice boost!
Consider diversifying your credit mix by adding different types of credit, such as installment loans or a secured credit card. This variety can positively influence your credit score when managed responsibly.
Being aware of your credit utilization is also crucial; aim to keep it below 30% of your available credit. Additionally, paying bills on time consistently can positively influence your credit score over time. Establishing a long credit history by keeping old accounts open, even if you don’t use them frequently, can further bolster your profile. Lastly, consider diversifying your credit mix by responsibly managing different types of credit, such as installment loans and revolving accounts. This holistic approach can ultimately enhance your creditworthiness.
Additionally, avoid opening too many new accounts at once, as each inquiry can temporarily lower your score. Regularly reviewing your credit report helps you stay informed about your financial health and enables you to track your progress over time. Building good habits around credit management will pay off in the long run, potentially leading to better loan terms and interest rates.
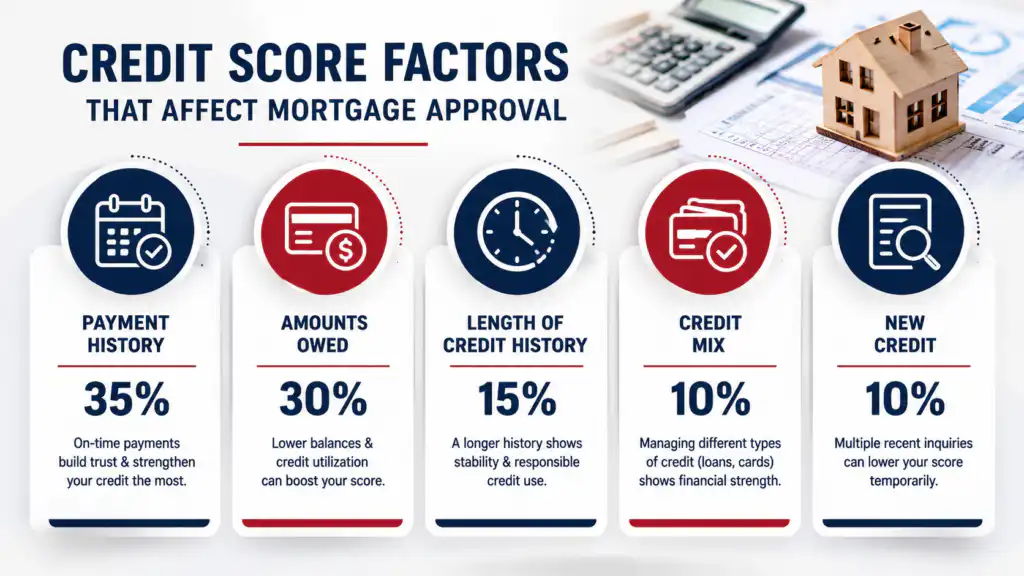
The chart in plain text: FICO’s general breakdown is payment history 35%, amounts owed 30%, length of credit history 15%, new credit 10%, and credit mix 10%. Utilization is part of amounts owed, not that entire category. The weight of a factor can differ with the credit profile. FICO explains these factors here.
5. Keep useful older accounts in perspective
Don’t close those old credit accounts, even if you’re not using them. They contribute to your credit history length, which plays a significant role in your score. Try making small purchases on these accounts and paying them off right away. This keeps them active without accumulating debt.
Remember, every little bit counts when it comes to boosting your credit score! Keeping older accounts can be beneficial, but it’s essential to balance that against any potential fees or the temptation to overspend. Before you make any big changes to your credit profile, especially as you prepare for a mortgage application, take a moment to consider how those changes might impact your overall credit health. It’s all about finding that sweet spot!
6. Pause unnecessary new credit
Pay Down Existing Debt
Making a dent in your current debt can significantly enhance your credit score. Focus on paying down high-interest credit cards first, as this can have a greater impact on your score. Plus, reducing your overall debt-to-income ratio will not only help your credit but also make you a more attractive borrower when it’s time to apply for that mortgage.
Monitor Your Credit Report
Regularly checking your credit report can help you spot any inaccuracies or signs of identity theft. You’re entitled to one free report each year from each of the three major credit bureaus, so take advantage of that. Keeping an eye on your credit can empower you to address issues before they affect your mortgage application.
7. Separate your credit score from your DTI
Understanding the difference between your credit score and debt-to-income ratio is key. While your credit score reflects your credit history and management, your DTI shows how much of your income goes toward paying debts. Keeping these separate in your mind can help you strategize better for your mortgage application. By reducing your debt load, you can improve your credit score while still working on managing your overall financial health.
Additionally, paying down high-interest debt can significantly lower your DTI, making you a more attractive candidate for lenders. Consider creating a budget that prioritizes essential expenses while allocating extra funds toward debt repayment. This approach not only improves your DTI but can also enhance your credit score over time.
Remember, lenders often evaluate both metrics when determining loan eligibility, so addressing them simultaneously can be beneficial. Regularly reviewing your financial situation will keep you informed and prepared for any upcoming applications.
8. Understand mortgage credit checks
Understanding the nuances of mortgage credit checks is crucial for maintaining a healthy credit score. When you check your own credit report, it’s considered a soft inquiry and won’t impact your score. However, be mindful that when a lender performs a hard inquiry, it can result in a slight decrease in your score. Additionally, different scoring models may yield varying results, so it’s important to consult with your advisor about timing your mortgage shopping inquiries to minimize any potential negative effects. Maintaining a good credit score involves monitoring not just your inquiries but also your overall credit activity. Understanding the specific criteria used by lenders can provide you with a competitive edge when applying for a mortgage.
Mortgage lenders will typically conduct a hard inquiry on your credit report, which can temporarily lower your score. However, multiple inquiries within a short period for the same type of loan are usually treated as a single inquiry. This means you can shop around for the best mortgage rates without significantly impacting your credit score; however, using a mortgage broker like Cederholm Mortgage Advisors can take all the heavy lifting off your shoulders when it comes time for shopping lenders and comparing apples to apples.
9. Preserve cash for the purchase
Maintaining a healthy savings balance is crucial when preparing for a mortgage. Ensure you have enough funds for the down payment, closing costs, and other expenses that may arise after the purchase. By strategically balancing debt repayment and cash reserves, you can enhance your financial profile without compromising your ability to cover essential costs.
Additionally, consider setting up a dedicated savings account specifically for these expenses to help you stay organized. Monitoring your spending habits can also provide insights into areas where you can cut back and save more effectively. Furthermore, having a strong financial cushion can provide peace of mind during the home-buying process. It’s important to remember that unexpected costs can arise, so being prepared financially will help you navigate any challenges that come your way.
10. Get a plan before making major changes
Collections, disputed accounts, thin credit history, and recently paid debts can require different approaches. Ask for a mortgage-readiness review before opening accounts or moving large amounts of money. No one can honestly promise a particular score increase or an approval on a fixed schedule. If you want to qualify for a home loan and prepare in advance with a solid game plan, these are the 10 ways to improve your credit score for a mortgage.
A practical first week
Day one: collect the three reports. Next: flag errors and verify payment reminders. Then: list card balances, limits, and monthly payments. Finally: bring that picture, your savings, and your buying timeline to a mortgage conversation. Share sensitive documents through a secure process, not an ordinary website comment.
Understanding your credit score is the first step toward a successful mortgage application. Take a close look at those reports and make sure everything checks out – any errors can hurt your score. Once you’ve got a clear picture of your finances, it’s time to strategize with your mortgage advisor about the best ways to boost your score before you apply.
Remember, this process doesn’t happen overnight, so be patient and stay proactive! Consider setting specific financial goals to guide your savings efforts. Creating a budget can help you identify areas where you can cut expenses and allocate more towards your down payment. Engaging with a financial planner may also offer personalized advice tailored to your situation. If you would like a recommendation or introduction to one, we can help. Contact us for more info.
Questions worth answering
How quickly can my credit score improve?
It depends on the information changing, creditor reporting dates, and the scoring model. Lower reported balances may show up after an account updates. Errors and older negative history can take longer. A specific increase is not guaranteed.
Should I pay every debt off before applying?
Not necessarily. Compare the qualifying benefit with the cash needed for your purchase and reserves. Ask for a review before making a large payoff.
What score do I need for a mortgage?
Requirements depend on the program, lender, and underwriting method. Credit is only one part of the review, alongside income, assets, debts, and the property. We can review the programs that fit your actual file.
Can you help if I am not ready to buy yet?
Yes. An early conversation can identify what to work on and when to check back. It is easier to plan before you have an offer deadline.
Turn the first-time homebuyer guide into your homebuying plan
Cederholm Mortgage Advisors can compare lenders and programs using your circumstances, then explain the payment, costs, and next steps. Contact Paul Cederholm and our team to start your homebuying plan.
Updated October 8, 2026.
Navigating the mortgage process can feel overwhelming, but we’re here to help simplify it for you. With a tailored approach, we’ll look at your unique financial situation and craft a strategy to enhance your credit score before you dive into homebuying. Whether you’re curious about different loan options or need clarity on associated costs, Paul Cederholm and our team are just a call away. Let’s make your dream home a reality, together!
If you’re wondering about your credit score and how it impacts your mortgage options, you’re not alone. Different lenders and programs have varying requirements, and understanding where you stand can help you make informed decisions. Even if you’re not quite ready to buy, having a chat can help you strategize on improving your score and preparing for the future. Reach out to Cederholm Mortgage Advisors today, and let’s map out your path to homeownership together!