 Conventional
Explore down payments, mortgage insurance and flexible property choices.
Home / Areas We Serve / Denver
DENVER HOME FINANCING
Denver offers very different home types within one city and county. Compare a Five Points condo, a Washington Park resale or a Central Park townhouse using the actual parcel, association documents and insurance quote. Paul Cederholm helps turn those details into a purchase or refinance plan.
Serving Denver metro and borrowers throughout Colorado. Compare home purchase, refinance, and home equity financing with Cederholm Mortgage Advisors, powered by Edge Home Finance.
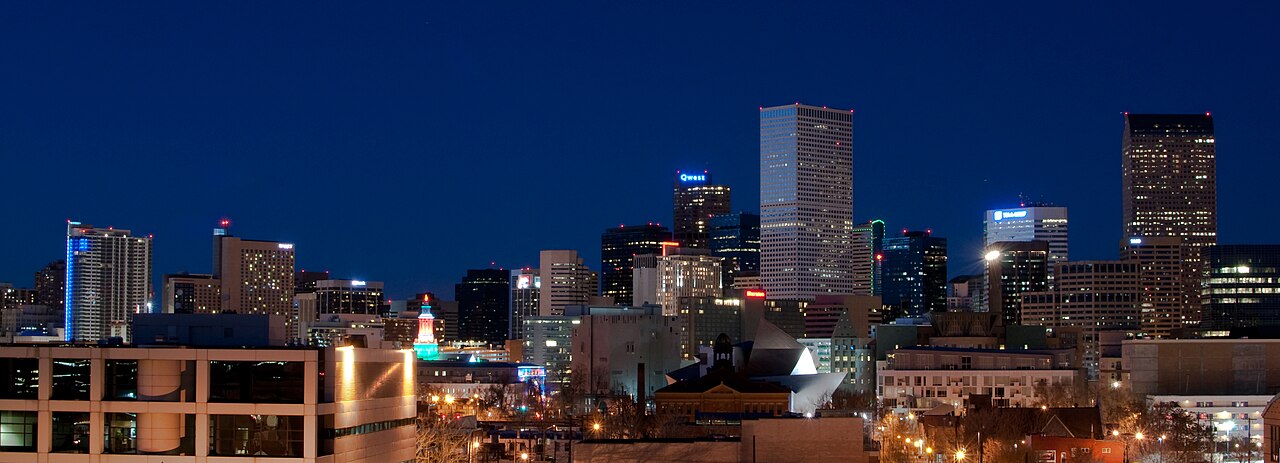
Denver’s official neighborhood map names Five Points, Highland, Sloan Lake, Washington Park, Cherry Creek, Montbello and Central Park. Those labels help describe location, but the mortgage file depends on the specific home. A historic house near Washington Park can raise inspection and repair questions; a condo near Union Station calls for an early review of the building and HOA; a newer attached home in Central Park may bring a different association package.
Denver is the City and County of Denver. Use the Denver assessor’s property characteristics and tax information for the parcel, then add a current homeowners insurance quote and any HOA dues. A listing payment or the seller’s escrow is only a starting point. Property condition, financing program and condo project review can change the practical choice.
The U.S. Census Bureau estimates 740,613 Denver residents as of July 1, 2025. Its 2020–2024 survey reports a 48.8% owner-occupied housing rate and a $94,718 median household income in 2024 dollars. About 18.0% of residents were under 18. These describe the city, not an individual buyer’s loan eligibility. Census QuickFacts.
Colorado’s economic development employer directory lists Denver International Airport, HealthONE, Kaiser Permanente and United Airlines among employers in Denver. Employer location does not establish where staff live or give them a special mortgage program. For buyers comparing commutes from Montbello, Central Park, Highland or farther south, keep transportation alongside the full housing payment. Colorado major-employer directory.
Start with a price and cash-to-close range, then test the same Denver address under each feasible loan. Include the current tax record, an insurance quote, association dues and any assessment. For a condo or townhouse, request the HOA budget, insurance and project details before assuming a particular loan will work. For an older detached home, inspections and property condition deserve equal attention.
If a listing is advertised as income-restricted or affordable, ask for the recorded covenant before making an offer. Denver’s housing department explains that some affordable homes have resale-price and buyer-income restrictions; its owner form also warns that a refinance may be limited by the maximum resale price. These terms belong to the specific property. Compare them with the Colorado down payment assistance guide and confirm any program’s current lender and property rules separately. Denver affordable-home covenant.
Compare the major ways to finance a Denver home. The right path depends on the borrower, property, occupancy and current program rules. Use the same taxes, insurance and HOA assumptions when comparing payments.
ConventionalExplore down payments, mortgage insurance and flexible property choices.
 FHA
Review FHA credit, down payment and property requirements.
 VA
See benefits and eligibility for qualified service members and veterans.
 USDA
Check how property location and household income affect USDA options.
 Jumbo
Learn how larger loan amounts change documentation and reserves.
 Non-traditional
Explore financing paths for income or property situations outside standard guidelines.
 Reverse mortgage
Review how reverse mortgages work and the ongoing homeowner obligations.
 Home equity loan / HELOC
Compare a home equity loan with a revolving line of credit.
 DPA
Find Colorado assistance programs and check geography and administrator rules.
Loan-guide images are reused from their linked pages. DPA stock photo: Alena Darmel, Pexels License; models are not CMA clients.
Denver’s Assessor FAQ explains that assessed value and mill levies both affect the tax bill, and that the assessor can provide ownership and property-characteristic records. Check the current tax statement and ask for a post-purchase estimate where relevant. Do not copy a citywide tax example into a loan scenario for a different property.
For a condo near Union Station or Cherry Creek, obtain project and association documents early. Ask about the master insurance policy, dues, reserves and special assessments. For any restricted home, review the recorded affordability covenant and title commitment. These documents can affect lender review, monthly cost and future refinancing.
Decide whether you want to change payment, term, cash access or loan structure. Compare the existing mortgage with a new loan using current property tax, insurance and HOA figures. If the home has an assistance second lien or affordable-housing covenant, obtain the actual payoff or consent requirements before assuming the refinance can proceed.
Review rate, closing costs, prepaids, new loan balance and total interest over the period you expect to keep the loan. A lower payment from extending the term is not automatically a lower total cost. Compare a home equity loan or HELOC if keeping the current first mortgage matters. No savings are promised.
Paul Cederholm (NMLS #1697336) leads Cederholm Mortgage Advisors, powered by Edge Home Finance (NMLS #891464). Your Denver mortgage broker helps you compare loan options, monthly payments, and cash to close with your goals in mind. We serve Denver metro and borrowers throughout Colorado, with conversations available by phone or video.
Meet Paul and our team · Google Maps and reviews · Experience.com reviews
Bring the listing, property type, target payment and your timing. We can compare practical loan scenarios, identify documents the property may require and review the Denver parcel and association information before you rely on a payment figure. See the home loan process.
Often, yes. The lender may need to review the building and HOA, including insurance, budget and any assessments. Request documents early so project questions do not surface only after an offer is accepted.
Use the same loan assumptions, then add each property’s verified taxes, insurance, association costs and likely maintenance. An inspection and the lender’s property review matter for the older home; the townhouse’s HOA and project documents deserve attention.
Do not assume so. Some Denver affordable homes have recorded covenants that limit refinancing or resale price. Read the property’s covenant and ask the city housing office and lender how it applies to the proposed loan.
Compare the new loan’s costs and payment over the time you expect to keep the home. If you may sell soon, a low payment might not recover closing costs. If you are changing term or taking cash out, compare total balances and interest too.
Denver neighborhood map · Denver Assessor FAQ · Denver affordable-home covenant · Denver Census QuickFacts. Sources reviewed September 28, 2026; the Census population estimate is for July 1, 2025 and the income and owner-occupancy measures are 2020–2024 survey data.
Explore the Colorado statewide guide or compare Centennial, Aurora and Parker. The Areas We Serve hub lists all published community guides.
Planning a Denver purchase or refinance? If you are not ready to move yet, start with a quick, no-obligation phone call. We can answer your first payment questions, review options using a property address if you have one, and map out next steps so you can plan with confidence.