You do not need to become a mortgage expert to buy your first home. You do need a clear order of operations, a realistic cash plan and people who explain what happens next. Start there. The house search gets easier when you know what fits.
Your first-time home buying roadmap
Some steps overlap. Your contract deadlines set the pace once an offer is accepted.
1. Set a payment you can live with
Your approved maximum and comfortable budget may be different. Add taxes, annual home insurance, mortgage insurance if applicable and HOA dues to principal and interest. Leave room for utilities, maintenance and the rest of your life.
Try the home affordability calculator and DTI calculator. Review your credit early with our mortgage credit preparation guide. Estimates are a starting point, not an approval.
2. Count the cash, beyond the down payment
- Down payment: depends on the loan and your eligibility. You do not automatically need 20%.
- Closing costs: lender, title, appraisal and other transaction charges. Your Loan Estimate identifies proposed costs.
- Prepaid items and escrow deposits: amounts for expenses such as interest, taxes and insurance.
- Earnest money: a contract deposit generally credited toward your funds at closing. Do not count it twice; refund rights depend on the contract.
- Before and after closing: inspection costs, moving, immediate repairs and reserves.
Down payment + transaction costs + prepaids and escrow deposits − credited deposits − approved credits = estimated remaining cash to close.
Keep your moving and emergency budget separate. The Closing Disclosure provides final transaction figures.
Ask about Colorado down payment assistance if it may fit. Assistance can have repayment obligations, income limits and other conditions. Review those before treating it as free money.
3. Get pre-approved before making an offer
Your mortgage advisor reviews income, debts, credit and assets to identify possible programs and a workable price range. Documents vary, but commonly include pay statements, bank statements and income records. Self-employed buyers may need additional business documents.
Ask what has actually been reviewed, which conditions remain and when the letter expires. Pre-approval is conditional. Final approval depends on the property and updated financial information. Start your homebuying plan with our team.
4. Find the home and write a workable offer
Choose an agent who explains the contract and local market clearly. Talk through property condition, commute, HOA documents, insurance availability and features that could affect financing.
Before submitting an offer, confirm the payment estimate for that address and proposed cash to close. Ask your agent about inspection, financing and appraisal protections, along with earnest-money deadlines. A competitive offer still needs to fit your finances.
5. Keep inspection and loan review moving
A home inspection helps you understand condition and repair needs. An appraisal addresses value for financing; it does not replace an inspection. Read the CFPB’s inspection guidance and our home appraisal guide.
Underwriting may ask for explanations or updated records. Respond promptly. Before taking on new debt, changing employment or moving large sums between accounts, ask your financing team how it could affect the loan. Keep a paper trail for funds used to close.
6. Review the documents and close
For most mortgages, you must receive the Closing Disclosure at least three business days before closing. Compare it with your Loan Estimate and ask about changes in terms, payment or cash required. The CFPB’s closing-document checklist can help.
Confirm wiring instructions by calling a known, independently verified number for the closing company. Do not trust a last-minute email changing account details. After signing, confirm when funding and possession occur under your contract.
7. Set up life after the keys
Save your closing records, confirm payment instructions and track your first due date. Budget for upkeep. Even on a fixed-rate mortgage, taxes, insurance and escrow changes can affect the total monthly bill. Our loan process guide gives you a broader view.
A quick introduction to financing strategies
- Temporary buydown: subsidizes early payments, then ends. Budget for the full payment.
- Permanent points: an upfront charge for a lower rate. Time needed to recover the cost matters.
- ARM: the rate may change after an initial period. Understand caps and possible payment increases.
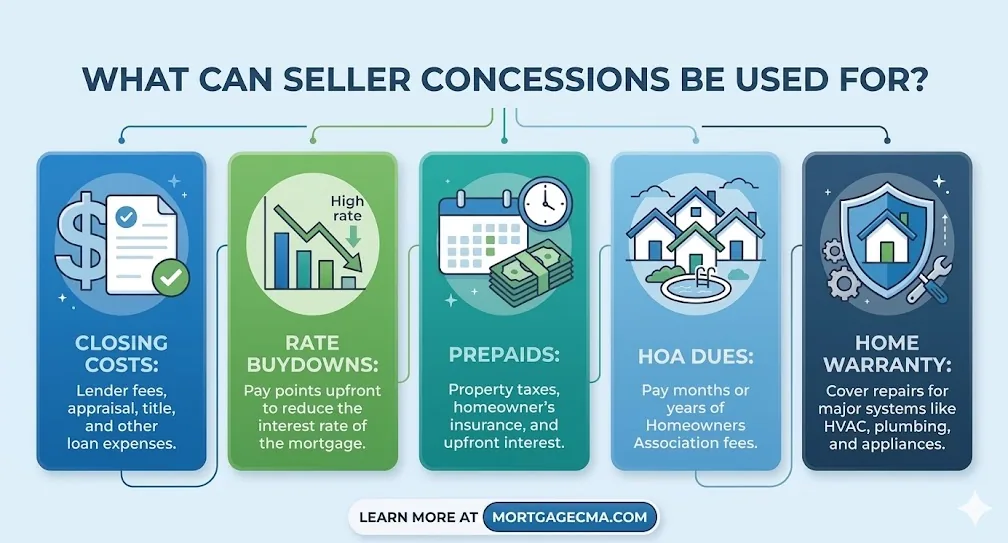
- Seller credits: cover permitted closing expenses within program limits, not your required down payment.
For the detailed comparison and offer checklist, read our home buyer’s financing and offer strategy guide. We can help you evaluate choices using your actual situation.
Common first-time buyer mistakes
- Shopping only by principal and interest. The rest of the housing payment still counts.
- Using every dollar to close. Leave room for repairs and everyday surprises.
- Assuming a refinance will solve a stretched budget. Future approval and rates are uncertain.
- Ignoring deadlines. Put contract dates and document requests on your calendar.
- Making financial changes without checking. A new car payment or unexplained deposit can complicate review.
Questions worth answering
Do I need 20% down?
No. Some programs allow a smaller down payment or no down payment for eligible borrowers. Compare qualification rules, mortgage insurance, fees and the full payment.
What counts as a first-time buyer?
Definitions vary by program. Some include buyers who have not owned a home during a specified prior period. Ask about the exact program you are considering.
How long does buying take?
The search can be quick or lengthy. Once under contract, financing, inspection, title work and contract deadlines affect closing. We will help you understand your transaction’s schedule.
Ready for a plan you can use?
Bring your questions, price range and savings goals. Paul Cederholm and the team at Cederholm Mortgage Advisors can help you understand the next step without expecting you to know every mortgage term. Start my homebuying plan or contact our team.
Reviewed October 8, 2026.
*Information, scenarios, and calculations are for educational and illustrative purposes only, not a loan offer, a commitment to lend, a rate quote or an approval. Programs, costs and qualification requirements depend on the borrower, property, selected lender and current guidelines. Examples are not guaranteed results. Our team can review the details for your situation.